Does Insurance Cover Online Therapy? What to Verify First
Published December 2025 · Last updated · Written by Paul Paradis, Editor · Educational information, not medical or mental-health advice
What changed: Reworded link and heading text without ranking claims: “best online therapy platforms compared” to “online therapy platforms compared”; “Best Online Psychiatry Services” to “Online Psychiatry Services Compared”; “best online psychiatry services” to “online psychiatry services compared”; plus 1 similar label. Earlier on October 30: Reworded the couples cash-pay tip so Ours is described as a former per-session option that Ours Privacy spun off from, citing AdExchanger (September 8, 2025).
Reviewed for educational clarity and safety language by Lisa Lewis, RN, BSN · Independent coverage guide using public insurer, platform, parity, and billing-code information
Usually, yes, but the useful question is whether your specific plan will pay before you book. Start with in-network-first options like Headway, Grow Therapy, Rula, Alma, or Sondermind for therapy and Talkiatry for psychiatry, then compare the shown copay against cash-pay subscriptions. So the real question to settle first is which insurance route should you verify first so you do not overpay or choose a platform your plan will not cover? It includes copay ranges, deductible warnings, superbill steps, denial questions, CPT-code prompts, and a short script for calling the number on your insurance card.
What a Marketplace plan has to include: HealthCare.gov lists behavioral health treatment such as psychotherapy and counseling as an essential health benefit that every Marketplace plan must cover. Those plans cannot charge more or deny coverage over a pre-existing mental health condition, and they cannot put yearly or lifetime dollar limits on mental health care (HealthCare.gov).
Where parity shows up on a bill: The same page explains that a plan's limits on mental health care cannot be stricter than its limits on medical and surgical care. That covers deductibles, copays and coinsurance, caps on the number of visits, and prior-authorization rules, so a therapy copay far above the plan's specialist copay is a reason to call the insurer and ask why.
Disclosure: No link on this site was placed by hand to pay us a commission, though a script from Sovrn Commerce (VigLink) that runs on every page may turn some ordinary links to outside stores and services into affiliate links that can earn us a commission at no extra cost to you. When it converts a link, our page code tags that link rel="sponsored" for search engines, but nothing on screen marks it as paid, so treat any outbound link as one that could earn us money. Our “best” and comparison guides do not score or rank services, and a possible commission never changes which services we list or what we say about them; see the affiliate disclosure.
Insurance details verified on Oct 25, 2026 from BetterHelp and Talkspace. Network lists change; ask your insurer and the platform before your first session.
This page sticks to coverage and claims: what your plan has to pay for, how to confirm it, how out-of-network reimbursement works, and what to do when a claim is denied. For cash prices, subscription math and low-cost routes without insurance, use the online therapy cost guide.
Insurance Coverage for Online Therapy: The Basics
Since the COVID-19 pandemic, telehealth coverage has expanded dramatically. Many private-plan and state Medicaid changes have stayed in place, but in Medicare most of the pandemic-era rules are still temporary and currently run through December 31, 2027. Most major insurance plans now cover virtual mental health services, including:
- Individual therapy sessions via video
- Psychiatry appointments for medication management
- Group therapy sessions
- Couples and family therapy (varies by plan)
- Psychological testing and assessments (some plans)
- Substance-use treatment, including telehealth-delivered IOPs
- Eating-disorder programs (varies; often additional auth required)
Parity: The Rules Behind Your Coverage
Two separate parity rules shape what a plan owes you for online therapy. One compares mental health benefits with medical benefits. The other compares a video visit with the same visit in an office.
Mental health parity (federal law)
The Mental Health Parity and Addiction Equity Act (MHPAEA) requires most group plans and ACA marketplace plans to cover mental health services at parity with medical and surgical services: the same kind of financial requirements (copay, deductible) and the same kind of treatment limits (visit caps, prior-authorization criteria). In practice that means:
- Similar copays for mental health and medical visits
- Similar deductibles and out-of-pocket maximums
- No unreasonable limits on therapy sessions
- Access to an adequate provider network
- Comparable prior-authorization requirements
- No more aggressive utilization review for behavioral than for medical care
The Department of Labor, which oversees job-based plans, spells out a few protections people rarely hear about. If a plan pays for out-of-network or inpatient care for medical conditions, it has to offer those benefits for mental health and substance use conditions as well. Most plans can't require prior authorization for every mental health treatment, and a plan shouldn't ask for a written treatment plan before paying for therapy when it asks for nothing comparable on the medical side. Annual dollar limits on mental health benefits can't be lower than the medical ones either. If you think a job-based plan is breaking these rules, the department's benefits advisors take calls at 1-866-444-3272 (U.S. Department of Labor).
State telehealth parity
Most states have laws or rules requiring private insurers to cover telehealth visits at the same rate as the equivalent in-person visit. Some go further and require "payment parity," so the provider gets the same reimbursement.
Practical implications: if your in-person therapy copay is $30, your telehealth therapy copay should be $30. If your in-person psychiatry visit needs no prior authorization, the telehealth version generally shouldn't either. These rules don't apply to certain self-funded employer plans (ERISA), short-term plans, or grandfathered plans, but they cover the vast majority of commercial insurance in 2026. State telehealth rules differ, so the telehealth laws by state guide is the place to check yours.
How Different Insurance Types Cover Online Therapy
Employer-Sponsored Plans (PPO, HMO, EPO)
The dominant category for working-age adults, and most of these plans cover mental health services. Almost all cover telehealth therapy at the same copay as in-person. PPOs typically also include out-of-network mental-health benefits with reasonable reimbursement after a deductible. HMOs require staying in-network. EPOs are HMO-like but often skip the referral requirement.
Check if your employer also offers an Employee Assistance Program (EAP), which may provide free therapy sessions. EAP sessions usually run 3–8 per year per concern; they don't require a copay and don't show up on your insurance EOB. If you exhaust EAP, your employer plan typically picks up therapy at the standard mental-health copay.
ACA Marketplace Plans
Mental-health and substance-use treatment are essential health benefits, so all marketplace plans must cover them. Coverage levels vary by plan tier (Bronze, Silver, Gold, Platinum). Bronze plans typically have the highest deductibles but lowest premiums; Gold and Platinum plans have the lowest deductibles and cost more upfront, but have lower per-session costs once you're using care. If you expect to use therapy weekly, the math often favors Gold or Silver over Bronze even with the higher monthly premium. Many marketplace plans have narrower mental-health networks than employer plans, so verify a specific therapist or platform is in-network before signing up.
High-Deductible Plans (HDHP)
You'll pay the negotiated rate (often $90–$140 for therapy) until you hit the deductible. After that, copay or coinsurance kicks in. The trade-off: HDHPs come with HSA eligibility, which lets you pay for therapy with pre-tax dollars.
Medicare
Original Medicare Part B covers outpatient mental-health telehealth at 80% after the Part B deductible: you pay the 20% coinsurance. Medicare Advantage plans often add extras (zero-copay therapy, free meditation app subscriptions). Medicare mental-health telehealth from home is not tied to the pandemic rules: it can continue after they end, but starting January 1, 2028, new patients will need an in-person visit within 6 months before their first home telehealth session, and everyone will need one in-person visit every 12 months, with limited exceptions. Congress set those dates in the Consolidated Appropriations Act, 2026 (CMS telehealth FAQ, updated October 8, 2026). See our Medicare & Telehealth Coverage guide for details.
Medicaid (and State-Named Programs)
Medicaid is a federally funded program administered by each state under its own name and rules. Many people searching for coverage may know their state's program by its local name rather than "Medicaid." Common examples include:
- MassHealth (Massachusetts)
- Medi-Cal (California)
- Apple Health (Washington)
- TennCare (Tennessee)
- Health First Colorado (Colorado)
- BadgerCare Plus (Wisconsin)
Every state Medicaid program covers some form of mental-health telehealth, though coverage details, specific platforms and accepted providers vary by state. Some telehealth platforms work with Medicaid in select states, while others don't accept Medicaid at all. Community mental health centers and Federally Qualified Health Centers (FQHCs) are usually the most reliable Medicaid-friendly access points. See our state-by-state Medicaid & State Healthcare Insurance Guide for a complete list of state program names and detailed coverage information.
Tricare (Military)
Tricare covers telehealth mental health services for service members, veterans, retirees, and their families. Active-duty members typically have zero out-of-pocket cost; reservists, retirees, and dependents may have small copays. The Tricare network for behavioral health is generally broad, and several major online platforms accept Tricare.
VA Health Benefits
Veterans enrolled in VA care can access telehealth therapy and psychiatry through VA Video Connect, often at no cost. The VA also runs specialized programs for PTSD, military sexual trauma, and substance use, all available remotely. Eligible veterans can additionally receive community-care referrals to in-network civilian providers when VA capacity is constrained.
Which Online Platforms Bill Insurance
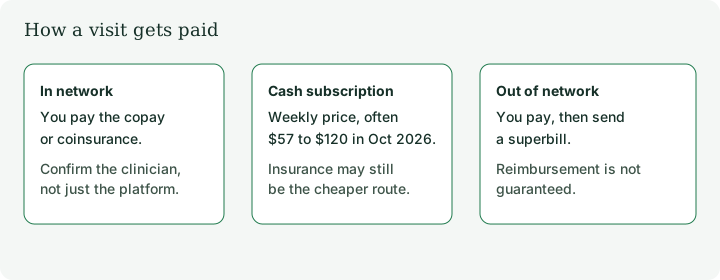
Using in-network providers typically results in the lowest out-of-pocket costs. Each platform's exact in-network insurer list changes regularly, but the pattern is consistent: the insurance-first platforms verify benefits before you book, hold your therapist's contract with the insurer, and submit claims on your behalf, so you only pay your real copay or coinsurance.
Insurance-first platforms
- Headway: Matches patients with in-network therapists and psychiatrists, who run their independent practices through Headway's billing infrastructure. Works with most major insurance plans, has strong nationwide therapist coverage, and shows you the copay before booking.
- Grow Therapy: A similar model to Headway, focused on making therapy accessible through insurance, with instant insurance verification and quick matching based on your needs and coverage.
- Rula: Insurance-first matching with in-network providers, often booking within 24–48 hours, with streamlined benefit verification. Available across most U.S. states.
- Alma: Therapist directory with detailed, transparent insurance information, many therapists in-network with major insurers, and out-of-network billing assistance.
- Sondermind: Insurance-friendly matching with verified, credentialed therapists.
- Talkiatry: In-network online psychiatry for medication management. Real psychiatrists with insurance billing rather than the membership model.
Subscription brands that now take some insurance
Some well-known online therapy platforms grew up on a subscription model, and the big consumer-facing names still handle insurance very differently:
- BetterHelp: Changed since our earlier versions: BetterHelp now says it accepts 125+ insurance plans, including Cigna, Aetna, Optum, and UnitedHealthcare, with copays as low as $15 for eligible members. Insurance may not show up in every state or signup, and insured members get limited messaging. Its providers do not directly accept Medicare, Medicaid or TRICARE for therapy. Cash price is $70–$100/week; HSA/FSA accepted.
- Talkspace: Says it is in-network with most major plans, including Aetna, Anthem, Cigna, and TRICARE, and that most insured members pay a $0 copay; it also works with Medicare and EAPs. Run their eligibility check before signing up; if you're covered, your cost may be a flat copay.
- Brightside: In-network with several insurers; specializes in depression and anxiety with prescribing.
- Online-Therapy.com / Calmerry: Subscription only, no insurance billing.
The general rule: if your priority is using insurance, start with Headway, Grow Therapy, Rula, Alma, Sondermind, or Talkiatry. If your priority is messaging-style support and predictable weekly cost, the subscription brands shine. For a side-by-side comparison of these platforms with the major subscription brands, see online therapy platforms compared.
How to Verify Coverage Step by Step
Don't trust the platform's auto-verification alone. Run these steps before your first session and you'll avoid surprise bills.
- Find your card and the behavioral-health number on it. You'll need your member ID, group number, and date of birth. Many plans contract a separate behavioral-health vendor (Optum, Carelon, Magellan, Beacon), and the number for them is usually on the back of your insurance card, separate from general customer service.
- Call and identify yourself. Tell the rep you want to confirm telehealth outpatient mental-health benefits.
- Ask the right specific questions. The script in the next section covers the exact wording. The single most important question is: "What is my in-network copay or coinsurance for outpatient therapy CPT 90834 or 90837 delivered by telehealth?"
- Get a reference number. Insurance reps make mistakes. A reference number tied to the call lets you appeal a wrong bill later with proof of the prior representation.
- Cross-check with the platform. When you sign up with Headway, Grow Therapy, Rula, Alma, or Sondermind, run their automated benefit check too; many can verify your benefits instantly. If the two answers disagree, ask the platform to investigate before your first appointment.
- Get it in writing. Ask for the plan's Summary of Benefits and Coverage. Insurers and job-based plans must give you this short, plain-language summary, along with a Uniform Glossary of insurance terms, and you can request a copy at any time, including for grandfathered plans (HealthCare.gov).
Exactly What to Say When You Call
Use this as a script. Read it almost word-for-word: insurance reps respond to specific terminology.
- "I'd like to verify telehealth mental-health benefits. My member ID is [your ID]."
- "Does my plan cover telehealth therapy, and what is my copay or coinsurance for an in-network outpatient psychotherapy visit, CPT code 90834 (45 minutes) or 90837 (60 minutes), delivered by telehealth?"
- "What about a psychiatric medication-management visit, CPT 99213 or 99214, and the initial psychiatric diagnostic evaluation, CPT 90791 or 90792?"
- "Do I have a separate behavioral-health deductible? What is it, and how much have I met this year?"
- "Are there annual session limits or visit caps for outpatient mental health?"
- "Do I need a referral or prior authorization for therapy or psychiatry?"
- "Are Headway, Grow Therapy, Rula, Alma, Sondermind, and Talkiatry in-network for me? Which other telehealth platforms are?"
- "If I see an out-of-network therapist, what percentage do you reimburse, and what is the out-of-network deductible?"
- "What is the place-of-service code my therapist should bill for telehealth: 02 (telehealth from a non-home location) or 10 (telehealth from the patient's home)?"
- "Could I have a reference number for this call, please, along with your name?"
Write the answers down in a single document with the date and reference number. Keep it where you can find it for the rest of the year.
What You'll Pay With Insurance
Your actual costs depend on your specific insurance plan. These are the terms that decide your share of each claim:
- Copay: A fixed amount per visit (typically $20-$50 for in-network)
- Coinsurance: A percentage of the visit cost (e.g., 20% after deductible)
- Deductible: Amount you pay before insurance kicks in
- Out-of-pocket maximum: Annual limit on your total costs
- Premium: The monthly fee you pay regardless of whether you use care
- Allowed amount: The most your plan will pay for a covered service, also called the eligible expense, payment allowance or negotiated rate. If a provider charges more than that, you may owe the difference (HealthCare.gov glossary).
In-Network vs. Out-of-Network
| Factor | In-Network | Out-of-Network |
|---|---|---|
| Copay/Coinsurance | Lower ($20-$50) | Higher (40-60% of cost) |
| Deductible | Often lower or waived | Usually applies first |
| Billing | Direct billing to insurance | Often requires reimbursement |
| Balance Billing | Not allowed | May be charged extra |
Balance billing is the bill for the gap between what the provider charges and the plan's allowed amount. HealthCare.gov's example: a $100 charge against a $70 allowed amount can leave you owing the other $30, while a preferred (in-network) provider may not balance bill you for covered services (HealthCare.gov glossary). For what those amounts add up to over a month, compared with cash-pay subscriptions, see the cost guide's worked examples.
Out-of-Network Reimbursement and Superbills
If your preferred therapist doesn't accept your insurance, you may still get partial reimbursement. A superbill is a detailed receipt your therapist provides showing the date of service, CPT code (the type of visit), ICD-10 code (the diagnosis the visit was billed under), the therapist's NPI and license number, and the amount you paid. If you have out-of-network mental-health benefits, you submit the superbill to your insurer and they reimburse you a percentage of either the cash-pay rate or their "allowed" rate, after the out-of-network deductible.
How to actually use one:
- Confirm with your insurer that you have out-of-network mental-health benefits and what they pay (commonly 50–70% after a separate OON deductible). Ask how the plan sets its allowed amount for out-of-network therapy, because the percentage applies to that figure, not to your therapist's fee.
- Pay your therapist directly each session.
- Ask the therapist for a monthly superbill: most generate them automatically through their EHR.
- Submit through your insurer's online portal or mail. Services like Reimbursify automate this for a small fee.
- Track reimbursements; appeal if amounts come back lower than your benefit description. A reimbursement that comes back short, or a claim refused because the therapist is outside the network, is a denial you can take through the appeal steps below.
Superbills do put a diagnosis code on file with your insurer. People with privacy concerns sometimes prefer cash-pay without a superbill; see telehealth privacy.
Common Reasons Therapy Claims Get Denied
Most denials fall into a small number of categories, and most of them are wrong CPT codes, missing prior authorization, or place-of-service errors that can be fixed. Knowing the category gets you to a fix faster.
- Missing prior authorization. Some plans require approval before starting therapy, or for sessions beyond a certain count. Your provider or platform can often handle this for you and can ask for a retroactive auth. Keep documentation of all authorizations: if a session is provided before auth is approved, the claim may be retroactively denied.
- Diagnosis not covered. A few plans don't cover certain diagnosis codes (V-codes, "couples counseling" without a primary diagnosis). The therapist may need to use a different but accurate diagnosis if one applies.
- Place-of-service code wrong. Telehealth visits should use POS code 02 or 10. If the therapist billed POS 11 (office) for a video visit, the claim may be denied as fraudulent. Easy fix.
- Not yet credentialed. If your therapist's enrollment with the insurer hasn't finished, claims will deny. Ask the platform's billing team for status.
- Out-of-network without OON benefits. If you don't have out-of-network coverage, an OON claim won't pay anything. Switch to an in-network therapist or accept it'll be cash-pay.
- Hit annual visit cap. Some plans cap outpatient mental-health visits per year. Request medical necessity documentation from your provider and appeal for additional sessions based on clinical need, and ask about EAP benefits as a supplement.
- Coordination-of-benefits issue. If the insurer thinks another plan should pay first (Medicare, spouse's plan), claims hold until you complete a COB form.
For any denial, request the specific reason in writing, ask your provider to submit any additional documentation, and ask your platform's billing team to handle the appeal. They do this every day; you don't have to.
How to Appeal a Denied Therapy Claim
When a fix at the billing level doesn't work, the formal appeal process takes over. The timelines below come from HealthCare.gov's guidance on internal appeals and external review.
Step 1: The written denial
Your insurer has to tell you in writing why it denied the claim: within 15 days when you were asking for prior authorization, within 30 days for care you already received, and within 72 hours for urgent cases. That letter, together with the Explanation of Benefits, is the paperwork your appeal answers.
Step 2: The internal appeal
You have 180 days (six months) from the denial notice to file. Fill in the insurer's appeal form, or write a letter with your name, claim number and member ID, and attach anything you want considered, such as a letter from your therapist on why the sessions are needed. Your state's Consumer Assistance Program can file the appeal for you. The insurer then has 30 days to decide an appeal for care you haven't had yet and 60 days for care you've already received, and it must send a written decision.
Step 3: External review
If the insurer still says no, you can ask an independent reviewer to look at the case. The written request is due within 4 months of the final denial. Reviews can cover any denial that turns on medical judgment, which is where "not medically necessary" therapy denials fall. A standard review is decided within 45 days and an expedited one within 72 hours, and the insurer must accept the reviewer's decision. The federally run process costs nothing; a state or contracted process can charge at most $25. When waiting would seriously endanger your health, you can request external review at the same time as the internal appeal.
Keep a paper trail
Keep copies of every EOB and denial letter, the appeal you sent, any letters from your therapist, and notes from each phone call with the date, time, and the name and title of the person you spoke to. Send copies and keep the originals. If you're stuck, contact your state insurance commissioner or Department of Insurance; for a job-based plan, the Department of Labor number above can also help.
Read Your EOB Carefully
After your therapy session is processed, you'll receive an Explanation of Benefits (EOB) from your insurer. It's not a bill; it's a record of what was billed, what your insurer "allowed," what they paid, and what you owe. Things to check:
- Allowed amount matches the rate the platform quoted.
- Member responsibility matches the copay you were told to expect.
- CPT code matches the type of visit you actually had.
- Place of service shows 02 or 10 for telehealth.
- Network status reads "in-network" if you booked through an in-network platform.
If anything looks wrong, call the insurer with your reference number and ask them to reprocess. Most billing errors are computer entry issues, not deliberate denials.
If You're Stuck Between Insurance and Cash
A surprising number of readers fall into a frustrating in-between zone: they have insurance, but the in-network mental-health network is thin, the only therapists with openings are out-of-network, and they don't have great OON benefits. Practical moves for that situation:
- Try every insurance-first platform: Headway, Grow Therapy, Rula, Alma, Sondermind. Each platform's network differs, even within the same insurer. One may show 6 in-network therapists where another shows 60.
- Ask the insurer for a "single-case agreement" if there are no in-network therapists with openings. It asks the insurer to cover an out-of-network therapist at in-network rates because it can't deliver the care through its own network.
- Consider a hybrid plan. Pay cash-pay for the therapist you actually click with, and use insurance for psychiatry/medication management through a separate platform like Talkiatry.
- Use HSA/FSA to soften the cash cost if your plan offers them.
- Switch insurance at next open enrollment if mental-health network access is genuinely poor: it's a legitimate reason to change plans.
No insurance at all, or a plan with very limited mental health coverage? Free peer support, reduced-fee collectives such as Open Path, sliding-scale community clinics, university training clinics, HSA/FSA funds and subscription pricing are compared in the cost guide and the low-cost telehealth guide, with HSA rules in HSA/FSA for Telehealth Coverage. If you pay a provider directly, the cost guide also explains your right to a good faith estimate and how to dispute a bill that comes in well above it.
Couples Therapy and Insurance: A Common Surprise
Many people are surprised to learn that most insurance plans don't cover couples or marriage counseling on its own. Insurance generally requires an individual diagnosis (anxiety, depression, adjustment disorder) for the policyholder; the couples work has to be documented as treatment for that diagnosis. Workarounds:
- One partner is the "identified patient," and the work is billed under their diagnosis. The other partner is included as a participant.
- Pay cash for a couples-specific platform like ReGain, which charges a weekly subscription. Ours, which used to charge per session, has since spun off a healthcare data-privacy company, Ours Privacy (AdExchanger, September 8, 2025), and we could not confirm it still offers therapy (checked October 30, 2026).
- Some EAPs include several couples sessions per year as a separate benefit: check with HR.
Be cautious of any therapist or platform offering to bill couples therapy under a fake medical diagnosis just so insurance will pay; that's billing fraud and can come back to bite you.
Online Psychiatry and Insurance
Psychiatry is more expensive than therapy cash-pay (cash-pay intakes run about $225–$500, depending on provider and state: Rula $225; Talkspace and Doctor On Demand $299, MDLIVE up to $299; Blossom Health $300; Talkiatry's cost guide $300–$500), so insurance matters even more. Insurance-first online psychiatry options:
- Talkiatry: Most established insurance-first telepsychiatry. Real psychiatrists, not only nurse practitioners. Network of major insurers.
- Headway: Some psychiatric prescribers run their practices through Headway with in-network billing.
- Grow Therapy: Adding more psychiatric prescribers; check coverage in your state.
- Rula: Includes prescribers in many states.
- Brightside: In-network with selected insurers; good for combined therapy + meds.
If you're starting fresh, see online psychiatry services compared and online medication management.
Privacy When You Use Insurance
Using insurance means a diagnosis code goes on your record with your insurer. Most people are fine with this; some prefer cash-pay for additional privacy (security clearances, custody situations, future life-insurance underwriting concerns). For a deeper look, see telehealth privacy and HIPAA in telehealth. Note that insurance claim records are HIPAA-protected: they aren't visible to your employer or random third parties.
Tricky Situations: Coverage Gotchas
A few less-common situations that trip people up:
- Out-of-state therapist. Most insurers will only pay for therapy if your therapist is licensed in the state where you are physically located during the session, even if they're licensed elsewhere. This affects college students, frequent travelers, and people who moved mid-treatment.
- Plan change mid-year. If you switch insurance mid-year, your therapist may not be in-network with your new plan. Check before the change date and either find a new in-network therapist or budget for cash-pay continuation.
- EAP overlap. If your employer EAP covers 5 sessions per year, those usually need to be used before you start insurance-billed therapy or you'll forfeit them. EAP sessions don't count toward your insurance deductible.
- Couples vs. individual diagnosis. If you start as individual therapy and pivot to couples work, the billing may need to change too: talk to the therapist.
- Adolescent and minor patients. Coverage usually requires parent or guardian consent; some teen-specific platforms (like Teen Counseling) handle the consent flow automatically.
- Diagnosis change mid-treatment. If your therapist updates your diagnosis, double-check that the new code is covered by your plan; rare but it happens.
What to Do Next
- Verify benefits. Use the script above to confirm your in-network and out-of-network mental-health coverage. Get a reference number.
- Pick an in-network platform. Try Headway, Grow Therapy, Rula, Alma, or Sondermind for therapy; Talkiatry for psychiatry.
- Confirm the copay you'll see. When the platform displays your verified copay, double-check it matches what your insurance rep said.
- Book a first session. If the therapist isn't a fit after 2–3 sessions, switch: most platforms allow free switches.
- Talk it through with our AI guide if you'd rather have someone walk you through the options out loud. Or use the insurance finder to match plans to platforms.
Frequently Asked Questions
Does insurance cover online therapy the same as in-person therapy?
Yes, in most cases. Federal mental-health parity rules require most plans to cover mental health services at the same level as physical health services, and state telehealth-parity laws require many plans to cover telehealth therapy at the same copay or coinsurance as the equivalent in-person visit. Coverage includes individual therapy, psychiatry, and often couples and group therapy. There are limited exceptions for grandfathered plans and a few self-funded employer plans.
How much will I actually pay with insurance for online therapy?
With in-network coverage, you typically pay a $20–$50 copay or 10–30% coinsurance per session. If your deductible isn't met, you may pay the full negotiated rate (often $90–$140) until you reach it. Out-of-network coverage usually starts only after a separate out-of-network deductible; the plan then reimburses part of its allowed amount, and you pay the rest plus anything the therapist charges above that amount. Your actual costs depend on your specific plan, including copay amounts, coinsurance rates, and whether your deductible has been met.
Which online therapy platforms accept insurance?
Insurance-first platforms include Headway, Grow Therapy, Rula, Alma, Sondermind, and Talkiatry (psychiatry). Talkspace and BetterHelp now both bill insurance (Talkspace: most major plans; BetterHelp: 125+ plans, varying by state). Both also take HSA/FSA cards.
How do I find an in-network online therapist?
Easiest path: sign up with an insurance-first platform such as Headway, Grow Therapy, or Rula, which can verify your benefits and match you to in-network providers automatically. Backup: check your insurance company's provider directory for telehealth-enabled therapists, or call the behavioral-health number on your insurance card and ask for the telehealth-enabled provider list.
Does Medicaid cover online therapy?
Yes in every state, though specific platforms and panels vary. Many Medicaid programs go by state names (MassHealth, Medi-Cal, Apple Health). FQHCs and community mental-health centers are reliable options. See Medicaid telehealth coverage.
Does Medicare cover online therapy?
Yes. Medicare Part B covers outpatient mental-health telehealth, typically with 20% coinsurance after the Part B deductible. Medicare Advantage plans often add extra benefits. See our Medicare telehealth guide.
What if my online therapy claim gets denied?
Request the denial reason in writing. Most denials are wrong CPT codes, missing prior authorization, or place-of-service errors and are fixable. Ask your provider to submit any additional documentation, and ask your platform's billing team to appeal: they do this routinely; prior-authorization problems in particular can often be resolved by having your provider handle the paperwork. If the appeal is unsuccessful, contact your state insurance commissioner.
Can I use my HSA or FSA if my insurance doesn't cover therapy?
Yes. HSA and FSA dollars can pay for licensed therapy, psychiatry visits, prescriptions, and most subscription platforms regardless of whether your medical insurance covers the service. This effectively discounts your cost by your marginal tax rate, often 20-30 percent. See HSA/FSA for telehealth.
Can I get reimbursed for out-of-network therapy?
If you have out-of-network benefits, you can pay your therapist directly, request a superbill (detailed receipt with diagnosis codes), and submit it to your insurance for partial reimbursement. Services like Reimbursify can help simplify this process. Reimbursement amounts depend on your specific out-of-network benefits.
What CPT codes should I ask about when verifying online therapy benefits?
For outpatient therapy, ask about CPT 90834 (45-minute session) and 90837 (60-minute session). For psychiatry, ask about 90791 or 90792 (initial diagnostic evaluation) and 99213 or 99214 (medication management follow-ups). Confirm the place-of-service code as 02 or 10 for telehealth.
What is mental health parity and how does it affect my coverage?
The Mental Health Parity and Addiction Equity Act requires most insurance plans to cover mental-health services at the same level as medical services. This means similar copays, deductibles, visit limits, and prior-authorization requirements. Combined with state telehealth-parity laws, it usually means you pay the same copay for online therapy as for an in-person visit.
Helpful Internal Resources
Pages on this site that build on this guide:
- Insurance & Costs hub: every coverage and pricing question on one page.
- Platforms hub: every platform we cover, sortable by features.
- Conditions hub: telehealth treatment by condition.
- Getting Started: first-step walkthroughs for new users.
- AI guide: chat through your specific situation.
- How to prepare for your telehealth appointment
- What to expect in your first online therapy session
- How to verify therapist credentials
- When telehealth isn't the right choice
- Online Therapy Cost Guide
- Telehealth Hidden Costs Explained
- HSA/FSA for Telehealth Coverage
- Medicare & Telehealth Coverage
- Medicaid & State Healthcare Programs
- Free & Low-Cost Telehealth Options
- Online Therapy Platforms Compared
- Online Psychiatry Services Compared
- Subscription vs. Pay-Per-Session
- How to Verify Therapist Credentials
- Online therapy guide
What this insurance coverage for therapy guide can and cannot do
Treat this insurance coverage for therapy guide as general background information only. Insurance coverage varies significantly by plan, employer, and state. Always verify your specific coverage directly with your insurance company before starting services.
This is not financial or legal advice. Coverage details change frequently, and the information here may not reflect your specific situation. Consult with qualified professionals for guidance on your insurance and healthcare decisions.
Sources
- Talkiatry: How much does a psychiatrist cost? (clinically reviewed August 30, 2024; checked October 24, 2026), source for the $300–$500 uninsured first-evaluation estimate and the $100–$300 follow-up range
- Rula FAQ: $225 for a 60-minute psychiatry intake and $175 per 30-minute follow-up without insurance (checked October 24, 2026)
- Doctor On Demand cost page: $299 for an initial 45-minute psychiatry consultation and $129 for a 15-minute follow-up without insurance (checked October 24, 2026)
- MDLIVE mental health: up to $299 for an initial psychiatry visit and $159 per follow-up before insurance (checked October 24, 2026)
- Blossom Health FAQ: cash rates of $300 for a first visit and $250 per follow-up (checked October 24, 2026)
- Congress.gov: H.R. 7148, Consolidated Appropriations Act, 2026 (Public Law 119-75, signed February 3, 2026); Medicare telehealth extensions are in section 6209 (checked October 24, 2026)
- BetterHelp: Frequently asked questions, including pricing and insurance (checked October 29, 2026)
- Talkspace: How Talkspace pricing works (checked October 29, 2026)
- 988 Suicide & Crisis Lifeline
- SAMHSA: Find help, including the National Helpline (1-800-662-4357) and FindTreatment.gov
- National Institute of Mental Health: Psychotherapies
- HHS Office for Civil Rights: HIPAA and telehealth
- Telehealth.HHS.gov: How do I protect my data and privacy?
- Medicaid.gov: Telehealth
- VA Telehealth Services
- U.S. Department of Labor: Mental health and substance use disorder parity (MHPAEA), checked October 29, 2026
- Open Path Collective
- CMS: Medicare telehealth FAQ (updated October 8, 2026)
- BetterHelp: Insurance, including the 125+ plans and Medicare, Medicaid and TRICARE limits (checked October 29, 2026)
- Company websites for the services named in this guide: Headway, Grow Therapy, Rula, Alma, Sondermind, Talkiatry, BetterHelp, Talkspace, Reimbursify, 7 Cups, ReGain.
- HealthCare.gov: Internal appeals, including denial-notice and decision deadlines (checked October 29, 2026)
- HealthCare.gov: External review, including filing window, decision times and the $25 fee cap (checked October 29, 2026)
- HealthCare.gov: Mental health and substance abuse coverage, essential health benefits and parity (checked October 29, 2026)
- HealthCare.gov: Summary of Benefits and Coverage (checked October 29, 2026)
- HealthCare.gov glossary: Allowed amount (checked October 29, 2026)
- HealthCare.gov glossary: Balance billing (checked October 29, 2026)
The person behind this insurance coverage for therapy guide
Paul Paradis, who founded and edits Telehealth Navigator, wrote and edited this insurance coverage for therapy guide, and his background includes more than two years working inside a forensic mental health hospital setting along with a personal and family life that mental health is part of. He reads the source documents most people don’t have time to get through, especially APA and NIMH guidance, CMS telehealth policy, and SAMHSA program documents, which he translates into plain English with links to the originals so readers can check the work for themselves. Since Paul is not a licensed clinician, this insurance coverage for therapy guide is not medical advice, and the full account of how each guide is researched, reviewed, and updated is in our editorial standards.